

Internal Control · 2025
In this section9 topics
- Internal Control — Board Opinion2 items
- Adequacy & Appropriateness of the Internal Control System1 item
- Internal Control Deficiencies1 item
- Audit Committee & Auditor Observations2 items
- Opinion on the Head of Internal Audit2 items
- Appointment, Discharge & Transfer of the Head of Internal Audit2 items
- Related Party Transactions2 items
- Counterparties & Transactions3 items
- Policy & Future Trends2 items
Internal Control — Board Opinion
Board Opinion — Introduction
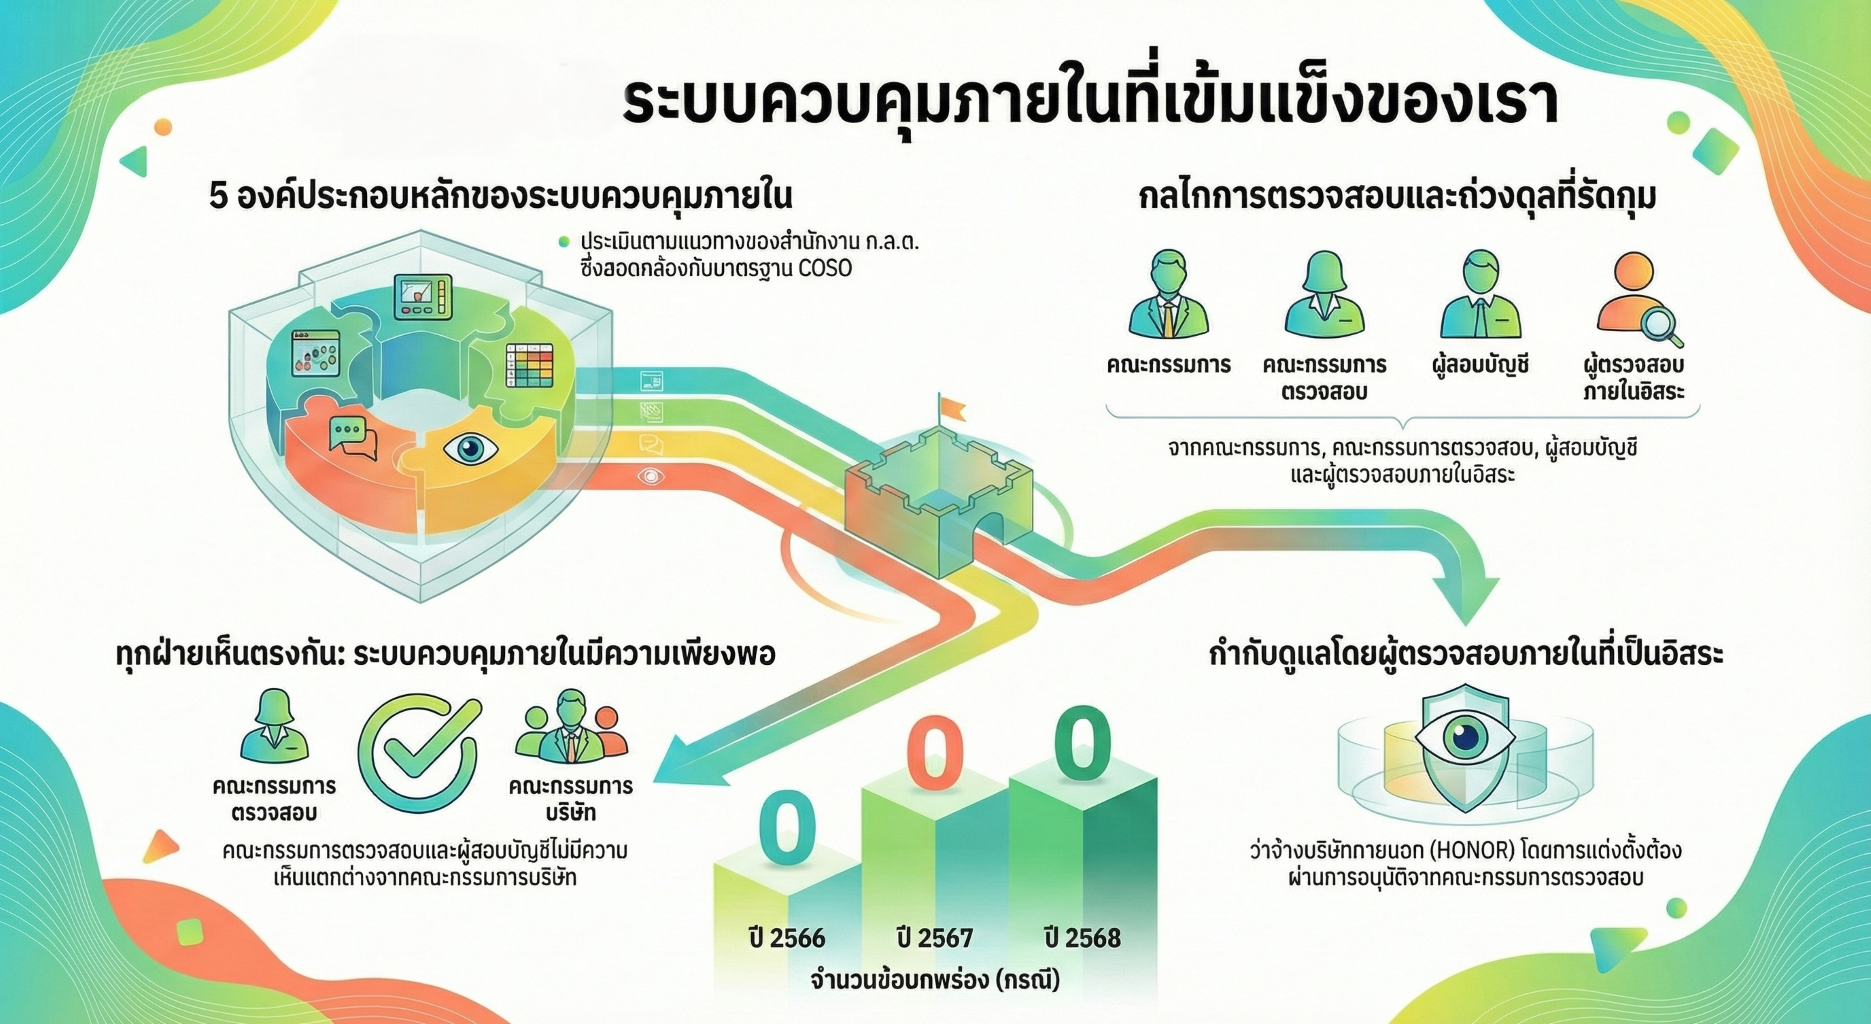
Summary of the Board's Opinion on Internal Control
The group of companies’ places emphasis on establishing a robust internal control system, which is a crucial factor supporting the efficient business operations of the company group. A sufficient and effective internal control system has been implemented, covering all areas of the group's operations, and complying with relevant laws, rules, and regulations. The group has implemented a check and balance mechanism that is adequate in safeguarding the group's assets, preventing their misuse, and mitigating potentially fraudulent activities. Approval authority and procedures have been clearly documented. Duties and responsibilities have been defined for executives and employees of each department to promote mutual checks and balances. The group has appointed an independent external agency, Honor Audit & Advisory Company Limited ("HONOR" or "Independent Internal Auditor"), as its internal auditor to audit departmental operations and ensure compliance with established policies and regulations, and report audit results directly to the Audit Committee. Additionally, EY Office Company Limited, the certified public accountant of the Company and its subsidiaries, has evaluated the internal control of the group and its subsidiaries concerning the preparation and presentation of financial statements to ensure their appropriateness and reliability. No significant deficiencies were identified that could affect the auditor's opinion of the financial statements of the Company and its subsidiaries for the auditing period of October 1, 2024 to September 30, 2025.
In this regard, the Company's Board of Directors held a meeting to assess the adequacy of the Group's internal control system. The assessment was based on the SEC Office's assessment form, which evaluates the internal control system in 5 parts as follows:
1. Control Environment
2. Risk Assessment
3. Control Activities
4. Information & Communication
5. Monitoring Activities
The Board of Directors concludes that the internal control system of the group of companies is sufficient and appropriate, in accordance with generally accepted accounting standards, the Office of the Securities and Exchange Commission and the Stock Exchange of Thailand regulations and announcements, and effectively implemented in reporting financial statements. The Company provides timely and accurate financial information, has a suitable and effective internal control system, and can adjust to changing situations effectively. The internal control system is compliant with relevant laws and regulations and has achieved its objectives. No significant issues were identified that could negatively impact the operations of the Group, including transactions with major shareholders, directors, executives, or related parties. The Audit Committee has no differing opinion from those of the Board of Directors.
Adequacy & Appropriateness of the Internal Control System
Internal Control Framework Used
| Framework | Detail |
|---|---|
| The Committee of Sponsoring Organizations of the Treadway Commission (COSO) | Honor Audit & Advisory Company Limited (HONOR) is the independent internal auditor appointed by the Company to assess, examine, and improve the adequacy and efficiency of the internal control system of the Company and its subsidiaries. HONOR assessed risks, prepared an annual internal audit plan, conducted inspections, and reported directly to the Audit Committee continuously to evaluate the efficiency and adequacy of the existing internal control system, compliance with relevant policies and procedures, and the suitability and reliability of the financial reports of the Company Group. The evaluation scope of the independent internal auditor encompasses components of internal control in accordance with the COSO framework in all 5 aspects, and assess risks within the internal control systems of the Company Group’s main operations. Following the assessment and audit of the Company Group's internal control system, the independent internal auditor provided recommendations for improvements, which were subsequently implemented and presented during the Audit Committee meeting. The auditor found that all identified issues were resolved within the specified timeframe, and no high-risk observations or suggestions were made in 2025. |
Internal Control Deficiencies
Number of Deficiencies
| Metric | Current Year | Previous Year | Two Years Ago |
|---|---|---|---|
| Total number of internal control system deficiencies (cases) | 0 | 0 | 0 |
Audit Committee & Auditor Observations
Audit Committee's Opinion Differs from the Board's
No
Auditor Has Observations on Internal Control
No
Opinion on the Head of Internal Audit
Head of Internal Audit
3160
Audit Committee's Opinion on the Head of Internal Audit
In 2025, the Audit Committee appointed Honor Audit & Advisory Company Limited (HONOR) to perform internal audit duties for the Company Group Ms. Piyamas Ruangsaengrob, head of the internal audit department, was designated by HONOR as the main person responsible for the performance of internal auditors for the Company Group. The Audit Committee assessed their qualifications, finding them to be adequate for the duties and possessing independence, experience, and relevant training.
In 2025, HONOR audited the internal control of the Group and presented its findings to the Audit Committee for quarterly acknowledgement.
Appointment, Discharge & Transfer of the Head of Internal Audit
Requires Audit Committee Approval
Yes
Description
The appointment or removal of the Group’s internal auditor must be approved or endorsed solely by the Audit Committee.
Related Party Transactions
Introduction
Related Party Transactions with Potential Conflicts of Interest
The Company acknowledges the significance of conducting business with transparency and considering all stakeholders. It follows related party
transaction guidelines to ensure transparency, avoid conflicts of interest, and secure approval from the management Board of Directors or shareholders'
meeting. The Company discloses all related party transactions accurately and completely, in the best interest of the Company and its shareholders. The
previous related party transactions between the Company and related parties were regular business dealings, conducted in compliance with established
guidelines to guarantee that the conditions of the related party transactions were consistent with typical trading conditions and market rates (arm's length
basis). The Company implemented the same protocols as those with third parties with similar or identical nature.
Has Related Party Transactions
Yes
Counterparties & Transactions
Monetary Unit
1000000
Counterparties with Potential Conflicts
| Name | Person / Juristic Person | Type of Business | Nature of Relationship | As of Date (YYYY-MM-DD) |
|---|---|---|---|---|
| Companies in the Univentures Public Company Limited Group | Juristic Person | /Investment business, real estate, energy business, consulting business, and others | Major shareholder and shares common directors
Share common directors
| 2025-09-30T00:00 |
| Companies within the Asset World Corp Public Company Limited group | Juristic Person | /Real estate development and management business, hospitality business group (Hospitality), and commercial real estate business group (Retail & Commercial Building) | Shares common directors with the parent company of Univentures Consulting
The subsidiary of the Company shares common directors with the parent company of Univentures Consulting
The ultimate major shareholder is a relative of the ultimate major shareholder of Univentures Consulting
| 2025-09-30T00:00 |
| Companies within the Thai Group Holdings Public Company Limited | Juristic Person | /Insurance, Life Insurance, and Automotive Hire Purchase Business | Share common directors with the parent company of Univentures Consulting
The subsidiary of the Company shares common directors with the parent company of Univentures Consulting
| 2025-09-30T00:00 |
| Companies within the Frasers Property (Thailand) Public Company Limited Group | Juristic Person | /Industrial real estate development business | Major shareholder shares common directors with the parent company of Univentures Consulting
| 2025-09-30T00:00 |
| Limited companies within the TCC Group | Juristic Person | /The business is a holding company, a real estate owner, and provides other services. | Shares common directors with the parent company of Univentures Consulting
The subsidiary of the Company shares common directors with the parent company of Univentures Consulting
Major shareholder shares common directors with the parent company of Univenture Consulting
| 2025-09-30T00:00 |
| Companies within the Thai Beverage Public Company Limited Group | Juristic Person | /Business of manufacturing and distributing various types of food and beverages | Share common directors with the parent company of Univentures Consulting
The subsidiary of the Company shares common directors with the parent company of Univentures Consulting.
| 2025-09-30T00:00 |
| Big C Supercenter Public Company Limited | Juristic Person | /Commercial business, manufacturing and distribution of consumer goods, and provision of various services. | The subsidiary of the Company shares common directors with the parent company of Univentures Consulting | 2025-09-30T00:00 |
| Amarin Corporations Public Company Limited | Juristic Person | /Print media business, producing printed materials and distributing books; exhibition organizing business, providing advertising services through print and online media; and television production and service business. | There are common directors with the Company | 2025-09-30T00:00 |
| S.A. Auto Co., Ltd. | Juristic Person | /Commercial truck import and export business | It is a business with common shareholders and directors. | 2025-09-30T00:00 |
| Unity Publication Limited Partnership | Juristic Person | /Printing Business, Other Printing | There are common shareholders and directors with subsidiaries | 2025-09-30T00:00 |
| Somjit Peumpremsuk | Person | Serves as a shareholder, director, and executive of the company. | 2025-09-30T00:00 |
Transactions by Counterparty
| Transactions |
|---|
| 3.34 · Necessity: It is a service agreement with standard business terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision services, with prices and contract terms comparable to those offered to general customers. · As of yesteryear: 3.1 · Nature of transaction: Service Income · Audit committee opinion: Such transactions are normal business transactions of the Group, with fair prices and conditions comparable to those with non-related parties (Arm’s length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 4.0 · Necessity: Used in the business operations of the group of companies. When compared with service offerings from other parties for the same liability limit, it was found that the insurance premium rates are comparable and the coverage conditions are more appropriate. · Description: 1. The Group has procured group personal accident insurance for its employees with S.E.C. Life Insurance Public Company Limited on an annual basis. 2. The Group has procured professional indemnity insurance with Indara Insurance Public Company Limited on an annual basis. 3. The Group has procured Director and Officer Liability insurance with Indara Insurance Public Company Limited on an annual basis. 4. The Group has procured building and property insurance for office buildings No. 163 and No. 123 with Indara Insurance Public Company Limited on an annual basis. · As of yesteryear: 2.39 · Nature of transaction: Other Expenses · Audit committee opinion: Normal business support transactions of the group of companies, which have reasonable premium rates and appropriate conditions, and are on normal commercial terms. · 0.97 · Necessity: Used in business operations for the group of companies, with contractual terms that are normal business practices, and with vehicle rental rates similar to the standard rates of Aeknane Capital Company. · Description: The Group of Companies has entered into a vehicle lease agreement with Aeknane Capital Co., Ltd. for use in its business operations. · As of yesteryear: 0.25 · Nature of transaction: Finance Cost · Audit committee opinion: The aforementioned transaction constitutes normal business support for the Group, with reasonable rental rates and normal commercial terms. · 1.29 · Necessity: Prices and payment terms are consistent with those provided to or received from other parties by the company. · Description: The Group of Companies has provided construction management and supervision services, with prices and contract terms comparable to those offered to general customers. · As of yesteryear: 1.29 · Nature of transaction: Trade Receivables · Audit committee opinion: Such transactions are normal business transactions of the Group, with fair prices and conditions comparable to those with non-related parties (Arm’s length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 1.21 · Necessity: Prices and payment terms are consistent with those provided to or received from other parties by the company. · Description: 1. The Group has procured group personal accident insurance for its employees with S.E.C. Life Insurance Public Company Limited on an annual basis. 2. The Group has procured professional indemnity insurance with Indara Insurance Public Company Limited on an annual basis. 3. The Group has procured Director and Officer Liability insurance with Indara Insurance Public Company Limited on an annual basis. 4. The Group has procured building and property insurance for office buildings No. 163 and No. 123 with Indara Insurance Public Company Limited on an annual basis. · As of yesteryear: 1.62 · Nature of transaction: Other Receivables · Audit committee opinion: Normal business support transactions of the group of companies, with reasonable insurance premiums and appropriate conditions, and on normal commercial terms. · 0.0 · Necessity: It is a service agreement with standard business terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision services, with prices and contract terms comparable to those offered to general customers. · As of yesteryear: 3.12 · Nature of transaction: Unbilled Receivables · Audit committee opinion: The aforementioned transactions are ordinary course of business for the group of companies, with fair prices and conditions comparable to those with unrelated parties (arm's length basis). For projects or segments where comparison is not feasible, the estimated gross profit margin at the time of considering the work was higher than the stipulated minimum gross profit margin. · 20.39 · Necessity: Prices and payment terms are consistent with those provided to or received from other parties by the company. · Description: The Group of Companies has entered into a vehicle lease agreement with Aeknane Capital Co., Ltd. for use in its business operations. · As of yesteryear: 15.56 · Nature of transaction: Finance lease liabilities · Audit committee opinion: The aforementioned transaction constitutes normal business support for the Group, with reasonable rental rates and normal commercial terms. · 0.76 · Necessity: Prices and payment terms are consistent with those provided to or received from other parties by the company. · Description: The Group of Companies has provided construction management and supervision services, with prices and contract terms comparable to those offered to general customers. · As of yesteryear: 0.0 · Nature of transaction: Service Income Received in Advance and Advances Received from Customers · Audit committee opinion: Such transactions are ordinary course of business for the group of companies, with fair prices and conditions comparable to those with unrelated parties (Arm’s length basis). For projects or segments where comparability is not feasible, the estimated gross profit margin at the time of considering the work was higher than the stipulated minimum gross profit margin. |
| 9.93 · Necessity: It is a service agreement with standard business terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision services, with prices and contract terms comparable to those offered to general customers. · As of yesteryear: 6.26 · Nature of transaction: Service Income · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 0.57 · Necessity: Prices and payment terms are consistent with those provided to or received from other parties by the company. · Description: The Group of companies has provided construction management and supervision services, with prices and contract terms comparable to those of general customers. · As of yesteryear: 1.42 · Nature of transaction: Trade Receivables · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 3.4 · Necessity: It is a service agreement with standard business terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision services, with prices and contract terms comparable to those offered to general customers. · As of yesteryear: 1.95 · Nature of transaction: Unbilled Receivables · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work was higher than the minimum gross profit margin specified. |
| 11.05 · Necessity: It is a service contract with standard business terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision/architectural and engineering design services, with prices and contractual terms comparable to those offered to general customers. · As of yesteryear: 40.47 · Nature of transaction: Service Income · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 0.89 · Necessity: Prices and payment terms are consistent with those provided to or received from other parties by the company. · Description: The Group of Companies has provided construction management and supervision/architectural and engineering design services, with prices and contractual terms comparable to those offered to general customers. · As of yesteryear: 4.79 · Nature of transaction: Trade Receivables · Audit committee opinion: The aforementioned transactions are ordinary business activities of the group of companies, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments where direct comparison is not possible, the estimated gross profit margin at the time of accepting the work was higher than the stipulated minimum gross profit margin. · 23.63 · Necessity: It is a service agreement with standard business terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision/architectural and engineering design services, with prices and contractual terms comparable to those offered to general customers. · As of yesteryear: 28.69 · Nature of transaction: Unbilled Receivables · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. |
| 1.67 · Necessity: It is a service agreement with standard business terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision services, with prices and contract terms comparable to those offered to general customers. · As of yesteryear: 3.3 · Nature of transaction: Service Income · Audit committee opinion: Such transactions are normal business transactions of the Group, with fair prices and conditions comparable to those with non-related parties (Arm’s length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 0.0 · Necessity: It is a service agreement with standard business terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision services, with prices and contract terms comparable to those offered to general customers. · As of yesteryear: 0.53 · Nature of transaction: Unbilled Receivables · Audit committee opinion: Such transactions are ordinary course of business for the group of companies, with fair prices and conditions comparable to those with unrelated parties (Arm’s length basis). For projects or segments where comparability is not feasible, the estimated gross profit margin at the time of considering the work was higher than the stipulated minimum gross profit margin. |
| 6.83 · Necessity: It is a service contract with standard business terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision services, with prices and contract terms comparable to those offered to general customers. · As of yesteryear: 1.36 · Nature of transaction: Service Income · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 0.03 · Necessity: for use in the business operations of the group of companies, and when compared to offers of goods and services from other parties under equivalent proposals, it was found that the price and service were superior. · Description: The Group of Companies purchased drinking water from Home and Office Delivery Co., Ltd. · As of yesteryear: 0.17 · Nature of transaction: Other Expenses · Audit committee opinion: The aforementioned transaction constitutes a normal business support transaction for the group of companies, with reasonable prices and service fees. · 1.09 · Necessity: Prices and payment terms are consistent with those provided to or received from other parties by the company. · Description: The Group of companies has provided construction management and supervision services, with prices and contract terms comparable to those of general customers. · As of yesteryear: 0.54 · Nature of transaction: Trade Receivables · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 0.78 · Necessity: Prices and payment terms are consistent with those provided to or received from other parties by the company. · Description: The Group of companies has provided construction management and supervision services, with prices and contract terms comparable to those of general customers. · As of yesteryear: 1.0 · Nature of transaction: Service Income Received in Advance and Advances Received from Customers · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work was higher than the minimum gross profit margin specified. |
| 1.35 · Necessity: It is a service agreement with standard business terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision/architectural and engineering design services, with prices and contractual terms comparable to those offered to general customers. · As of yesteryear: 4.01 · Nature of transaction: Service Income · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 0.43 · Necessity: Prices and payment terms are consistent with those provided to or received from other parties by the company. · Description: The Group of Companies has provided construction management and supervision/architectural and engineering design services, with prices and contractual terms comparable to those offered to general customers. · As of yesteryear: 0.73 · Nature of transaction: Trade Receivables · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 0.05 · Necessity: It is a service agreement with standard business contract terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision/architectural and engineering design services, with prices and contractual terms comparable to those offered to general customers. · As of yesteryear: 1.07 · Nature of transaction: Unbilled Receivables · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work was higher than the minimum gross profit margin specified. |
| 199.21 · Necessity: It is a service agreement with standard business terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision/architectural and engineering design services, with prices and contractual terms comparable to those of general customers. The majority of service income is derived from One Bangkok Co., Ltd. (formerly Kasemsubwattana Co., Ltd.). · As of yesteryear: 253.6 · Nature of transaction: Service Income · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 6.34 · Necessity: Used in business operations for the corporate group, with prices comparable to those of other companies offering similar services. · Description: 1. The Group has service fees and prepaid expenses from a contract with T.C.C. Technology Co., Ltd. (lessor) for the lease of computer equipment and information technology services to the Group. 2. The Group has service fees, prepaid expenses, and deposits for services with North Park Golf & Sports Club Co., Ltd. for the business operations of the Group. 3. The Group has service fees and venue usage for the National Engineering Conference 2025 at the Queen Sirikit National Convention Center with N.C.C. Management & Development Co., Ltd. for the business operations of the Group. · As of yesteryear: 5.7 · Nature of transaction: Other Expenses · Audit committee opinion: The aforementioned transactions are normal business transactions of the Group, and the Audit Committee has considered and is of the opinion that the transactions are fair and reasonable. · 13.18 · Necessity: Prices and payment terms are consistent with those provided to or received from other parties by the company. · Description: The Group of Companies has provided construction management and supervision/architectural and engineering design services, with prices and contractual terms comparable to those offered to general customers. · As of yesteryear: 32.72 · Nature of transaction: Trade Receivables · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 0.98 · Necessity: Prices and payment terms are consistent with those provided to or received from other parties by the company. · Description: 1. The Group's prepaid service fees and expenses arise from a contract with T.C.C. Technology Co., Ltd. (the lessor) for the lease of computer equipment and information technology services to the Group. 2. The Group has prepaid service fees, expenses, and service deposits with North Park Golf & Sports Club Co., Ltd. for use in the Group's business operations. · As of yesteryear: 0.59 · Nature of transaction: Other Receivables · Audit committee opinion: The aforementioned transactions are normal business transactions of the Group, and the Audit Committee has considered and is of the opinion that the transactions are fair and reasonable. · 8.06 · Necessity: It is a service agreement with standard business contract terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision/architectural and engineering design services, with prices and contractual terms comparable to those offered to general customers. · As of yesteryear: 32.8 · Nature of transaction: Unbilled Receivables · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 1.5 · Necessity: Used in business operations for the corporate group, with prices comparable to those of other companies offering similar services. · Description: The Group holds a deposit for services with North Park Golf and Sports Club Co., Ltd./North Park Real Estate Co., Ltd. for use in the Group's business operations. · As of yesteryear: 2.8 · Nature of transaction: Other Non-Current Assets · Audit committee opinion: The aforementioned transactions are normal business transactions of the Group, and the Audit Committee has considered and is of the opinion that the transactions are fair and reasonable. · 2.07 · Necessity: Prices and payment terms are consistent with those provided to or received from other parties by the company. · Description: 1. The Group has service fees and prepaid expenses from a contract with T.C.C. Technology Co., Ltd. (lessor) for the lease of computer equipment and information technology services to the Group. 2. The Group has service fees, prepaid expenses, and deposits for services with North Park Golf & Sports Club Co., Ltd. for the business operations of the Group. 3. The Group has service fees and venue usage for the National Engineering Conference 2025 at the Queen Sirikit National Convention Center with N.C.C. Management & Development Co., Ltd. for the business operations of the Group. · As of yesteryear: 1.93 · Nature of transaction: Other Payables · Audit committee opinion: The aforementioned transactions are normal business transactions of the group of companies, and the Audit Committee has considered them and is of the opinion that the transactions are fair and reasonable. |
| 0.0 · Necessity: It is a service agreement with standard business terms and similar gross profit margins. · Description: The Group of Companies has provided construction management and supervision/architectural and engineering design services, with prices and contractual terms comparable to those offered to general customers. · As of yesteryear: 0.28 · Nature of transaction: Service Income · Audit committee opinion: Such transactions are normal business operations of the Group, with fair prices and conditions comparable to those with non-related parties (Arms length basis). For projects or segments that cannot be compared, the estimated gross profit margin at the time of considering the work is higher than the minimum gross profit margin specified. · 0.31 · Necessity: It is used for the business operations of the group of companies. After comparing the suitability of service proposals with other providers, it was concluded that this service proposal is more appropriate and consistent with the nature of the service usage and the company's business operations than other service offerings. · Description: Publication production costs · As of yesteryear: 0.05 · Nature of transaction: Other Expenses · Audit committee opinion: Such transactions are normal business support transactions for the group of companies, with reasonable prices and service fees. · 0.01 · Necessity: It is used for the business operations of the group of companies. After comparing the suitability of service proposals with other providers, it was concluded that this service proposal is more appropriate and consistent with the nature of the service usage and the company's business operations than other service offerings. · Description: Publication production costs · As of yesteryear: 0.0 · Nature of transaction: Other Payables · Audit committee opinion: Such transactions are normal business support transactions for the group of companies, with reasonable prices and service fees. · 0.27 · Necessity: It is used for the business operations of the group of companies. After comparing the suitability of service proposals with other providers, it was concluded that this service proposal is more appropriate and consistent with the nature of the service usage and the company's business operations than other service offerings. · Description: Deposit for print media production · As of yesteryear: 0.27 · Nature of transaction: Other Non-Current Assets · Audit committee opinion: Such transactions are normal business support transactions for the group of companies, with reasonable prices and service fees. |
| 0.0 · Necessity: Used in business operations for the corporate group, with prices comparable to those of other companies offering similar services. · Description: In 2024, the company incurred water and electricity costs with S.A. Auto Co., Ltd. due to the utilization of a portion of its premises for the company's business operations. · As of yesteryear: 0.1 · Nature of transaction: Other Expenses · Audit committee opinion: The aforementioned transactions are normal business transactions of the Group, and the Audit Committee has considered and is of the opinion that the transactions are fair and reasonable. · 0.01 · Necessity: Used in business operations for the corporate group, with prices comparable to those of other companies offering similar services. · Description: In 2024, the company incurred water and electricity costs with S.A. Auto Co., Ltd. due to the utilization of a portion of its premises for the company's business operations. · As of yesteryear: 0.2 · Nature of transaction: Other Payables · Audit committee opinion: The aforementioned transactions are normal business transactions of the Group, and the Audit Committee has considered and is of the opinion that the transactions are fair and reasonable. |
| 0.0 · Necessity: A comparison of the suitability of price and product proposals with other vendors has been conducted. It is concluded that this proposal is more appropriate and better aligns with the company's business operational requirements. · Description: In 2024, a subsidiary of the Group entered into a vehicle purchase agreement for one unit with Mr. Somjit Piampremsuk for the company's operations. · As of yesteryear: 0.6 · Nature of transaction: Other Payables · Audit committee opinion: The aforementioned transactions are normal business transactions of the Group, and the Audit Committee, having considered them, is of the opinion that the transactions are fair and reasonable. |
| 0.0 · Necessity: Used for the business operations of the group of companies. When compared to equivalent offers of goods and services from other parties, Unity Publication Limited Partnership provides better pricing and services. · Description: The group's affiliated companies have produced printed media or purchased office supplies from Unity Publication Limited Partnership. · As of yesteryear: 0.02 · Nature of transaction: Other Expenses · Audit committee opinion: Such transactions are normal business support transactions for the group of companies, with reasonable prices and service fees. |
Policy & Future Trends
Policy, Measures & Approval Process
Currently, UVC (formerly UVCAP) holds 38.12% of the Company's issued and paid-up registered capital (data as of February 5, 2025). As UVC is a company held by UV, which has numerous related individuals or companies, the Group has a guideline for verifying and identifying related parties with connected transactions with the Group to ensure that connected transactions are fully approved, reviewed, and disclosed. The Group already maintains a database of related parties that have previously transacted with the Group, enabling immediate identification of relationships when transacting with such companies again. Additionally, whenever the Group bids on new projects, it will always verify the names of directors and shareholders of the project's client. In cases where the client is a company whose shareholders are other companies, the information of directors and shareholders of those shareholding companies must be verified until the ultimate shareholder of all clients is identified, to determine whether the client is considered a related party.
The Company has approved principles regarding commercial agreements with general trading conditions for business transactions between the Company and its subsidiaries with directors, executives, or related persons, which have commercial agreements similar to those a reasonable person would conduct with general counterparties in the same situation. The Company will prepare a summary report of such transactions to be submitted to the Audit Committee every quarter.
The Company prioritizes transparent consideration of various transactions that are primarily beneficial to the Company. For this reason, the Company emphasizes preventing transactions that may involve conflicts of interest, connected transactions, or intercompany transactions, based on the following key principles:
Company directors and executives must inform the Company of any relationships or connected transactions in business that may give rise to conflicts of interest.
Avoid connected transactions with directors, executives, or related persons that may create conflicts of interest with the Company. In cases where such transactions are necessary, the connected transactions must be presented to the Audit Committee for consideration and opinion before being submitted for approval to the Board of Directors and/or the shareholders' meeting of the Company (as the case may be), in accordance with the connected transaction rules prescribed by the Stock Exchange of Thailand, the Capital Market Supervisory Board, and the Securities and Exchange Commission ("SEC"), and in accordance with good corporate governance principles.
Directors, executives, or related persons may conduct transactions with the Company or its subsidiaries only when such transactions have been approved by the Board of Directors and/or the shareholders' meeting of the Company (as the case may be), in accordance with the connected transaction rules of the Stock Exchange of Thailand, the Capital Market Supervisory Board, and the SEC, unless such transactions fall into one of the following categories:
(a) Transactions that are normal business transactions or normal business support transactions, which have commercial agreements similar to those a reasonable person would conduct with general counterparties in the same situation, with commercial bargaining power free from the influence of their status as a director, executive, or related person, as the case may be, and are commercial agreements or business support.
(b) Loans in accordance with employee and staff welfare regulations.
(c) Transactions where one or both counterparties of the Company are in the status of
Subsidiaries in which the Company holds not less than 90% of all issued shares of the subsidiary, or
Subsidiaries in which directors, executives, or related persons hold shares or have an interest, whether directly or indirectly, not exceeding the amount, rate, or characteristics as prescribed by the Capital Market Supervisory Board.
(d) Transactions of a type or value not exceeding the rate prescribed by the Capital Market Supervisory Board.
Executives and employees must strictly adhere to the Company's regulations and business ethics to ensure that the Company is trusted and relied upon by all stakeholders, and information must be disseminated to foster understanding of employee conduct throughout the Company.
For the approval of connected transactions of the Company, any person who may have a conflict of interest or a stake in the transaction shall not be able to participate or vote in the approval of such transaction. Furthermore, the Company shall comply with the Notification of the Stock Exchange of Thailand Board of Governors Re: Disclosure of Information and Operations of Companies in Connected Transactions B.E. 2546, Chapter 5: Procedures for Connected Transactions, including laws on securities and stock exchange regulations, notifications, orders, or requirements of the Securities and Exchange Commission (SEC), the Capital Market Supervisory Board, and the Stock Exchange of Thailand related to such matters. The Company shall also comply with the requirements regarding the disclosure of connected transactions of the Company and its subsidiaries according to accounting standards prescribed by the Federation of Accounting Professions under the Royal Patronage, and shall disclose connected transactions in the notes to the financial statements audited or reviewed by the Company's auditor and in the Company's annual registration statement (Form 56-1).
Furthermore, for connected transactions that are normal business operations, the connected transaction policy grants the Company's management the authority to approve such transactions. However, to protect the interests of the Group, including transparency in controlling and supervising connected transactions, the Company has considered and approved guidelines for proving the fairness of connected transactions that are normal business transactions, to ascertain whether the connected transactions that the Company or its subsidiaries agree to enter into are normal business transactions with fair prices and conditions. The summarized details of the guidelines are as follows:
"Normal business transactions" refer to the provision of services to, or the purchase of goods/services from, persons related or connected to the Company, which are involved in the core business operations of the Group, such as providing construction management and supervision consulting services, and architectural and engineering design services, interior design, and historical site conservation, etc., and which have fair prices and conditions similar to those that a reasonable person would conduct with general counterparties in the same situation, with commercial bargaining power free from the influence of their status as a director, executive, or related person (Arm’s Length Basis), for example.
Trading under prices and conditions that the Company or its subsidiaries receive from or offer to the general public, or
Trading under prices and conditions that related persons offer to the general public, or
Trading under prices and conditions that the Company can demonstrate are offered by businesses similar to the Company to the general public, etc.
If the provision of services to, or the purchase of goods/services from, persons related or connected to the Company, which are involved in the core business operations of the Group, have fair prices and conditions, then they shall be considered normal business transactions, and management shall have the authority to approve such transactions. Executives must compare the expected gross profit margin from services provided in projects that involve construction management and supervision consulting, or architectural and engineering design services, interior design, and historical site conservation, which are connected transactions ("RPT Projects"), with the estimated gross profit margin for projects of similar nature and complexity provided to external parties. In cases where the Group has never provided services for such a project before and there are no other comparable projects, it must be considered whether the RPT Project's gross profit margin is higher than the minimum set in the Group's professional service fee calculation regulations, to prove the fairness of the price for services in the RPT Project. Furthermore, executives must examine the terms of the draft service contract to determine if there are any non-commercial terms to assess the fairness of the terms for services in the RPT Project. However, if executives determine that the RPT Project has unfair prices and/or contract terms or is not a normal commercial transaction, the Company shall collect relevant information, including reasons and necessity, and present it to the Audit Committee for consideration of the appropriateness of approving the transaction.
This guideline for proving the fairness of connected transactions that are normal business transactions will help ensure that business operations with related parties are transparent, verifiable, and have fair terms and prices comparable to conducting business with other parties, in order to protect shareholders' interests from the transfer of benefits to related parties of the Group.
Future Trends in Related Party Transactions
The Group anticipates that intercompany transactions arising from its ordinary course of business will continue to exist in the future as necessary and appropriate, such as providing management consulting and construction supervision services, architectural design, engineering design, other services, and insurance with companies that are related parties to the Group, etc. Such intercompany transactions will be conducted under normal commercial terms and conditions, with clearly defined guidelines for proving the fairness of entering into intercompany transactions that are ordinary business transactions. The prices and conditions must be appropriate and fair, taking into account the best interests of the Company and its subsidiaries. Furthermore, the Audit Committee is designated to verify compliance with the Company's and its subsidiaries' criteria to ensure that the policy for entering into intercompany transactions and the guidelines for proving the fairness of intercompany transactions that are ordinary business transactions are fully and correctly complied with.